Introduction:
Living and working in the USA offers higher salaries, new opportunities, and a global lifestyle. But many NRIs assume that being abroad automatically exempts them from Indian taxes. The truth? Misunderstanding your residential status can lead to costly mistakes, from unexpected tax bills to penalties. Before diving into common pitfalls, it’s important to know how Indian law defines NRI status and why it matters for taxation.
How to determine that an Individual is NRI
Residential status determines taxability in India and is assessed each financial year based on an individual’s presence in the country.
| Residential Status | Criteria | Taxability |
| Resident & Ordinarily Resident (ROR) | Stayed ≥ 182 days in India OR ≥ 60 days and ≥ 365 days in preceding 4 years | Taxed on global income (Indian + Abroad) |
| Resident but Not Ordinarily Resident (RNOR) | Resident who stayed ≤ 729 days in last 7 years OR Non-Resident in ≥ 9 of 10 preceding years | Taxed on Indian income only; (foreign income earned & Income received from abroad is exempt) |
| Non-Resident (NR) | Does not meet basic residency conditions | Taxed only on income received in India or sourced from India |
| Deemed Resident | Indian citizen with Indian income > ₹15 lakh, not liable to tax elsewhere | Treated as RNOR |
| Special Relaxations | Citizens leaving India for work/crew or visiting India | Stay thresholds adjusted (120–182 days for visits, 182 days for leaving) |
Why Residential Status Is Crucial
- Residents are taxed on their global income
- NRIs are taxed only on income that is earned or received in India
Even a short stay in India can change tax status; therefore, tracking days of presence in India is essential for accurate compliance.
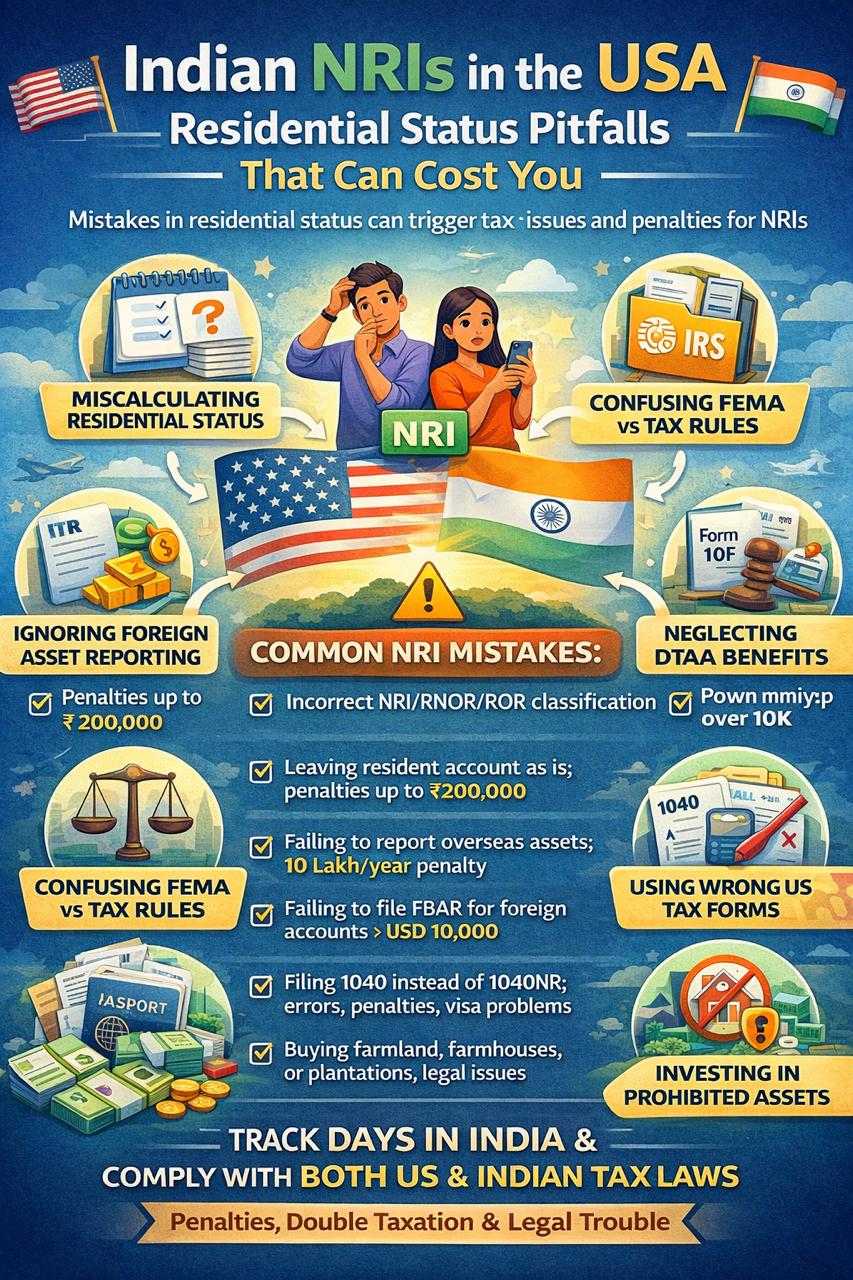
Top NRI Compliance Pitfalls for Indians in the USA
Understanding your residential status is crucial, because misclassification can trigger several compliance pitfalls under both Indian and US laws, affecting taxes, banking, and investments.
| Pitfall | Explanation | Consequences |
| Miscalculating Residential Status | Incorrect NRI, RNOR, or ROR classification | Global income may become taxable in India |
| Conflicting Definitions (FEMA vs Tax Act) | Tax Act uses days of stay; FEMA considers intent to stay abroad | Confusion in compliance, banking, and investments |
| Not Converting Bank Accounts | Resident accounts must become NRE/NRO | Penalties: up to 3× balance or Rs. 2,00,000 + ₹5,000/day |
| Ignoring Foreign Asset Reporting | RORs must report foreign assets in ITR | Penalties up to ₹10 lakh/year under Black Money Act |
| Missing US Filing Requirements | FBAR filings required for accounts > USD 10,000 | Heavy US penalties |
| Overlooking DTAA Benefits | TRC & Form 10F must be filed to claim tax credits | Risk of double taxation |
| Using Wrong US Tax Forms | Filing 1040 instead of 1040NR for non-residents | Penalties, visa/green card complications |
| Investing in Prohibited Assets | NRIs cannot buy farmland, farmhouses, or plantations | Legal action in India |
How to Avoid Common NRI Compliance Pitfalls
To stay compliant and avoid costly mistakes, NRIs should follow these key steps and best practices.
| Action | Details / Recommendation |
| Track Stay Days Accurately | Maintain a meticulous record of days spent in India each financial year to determine your correct residential status. |
| Convert Bank Accounts Promptly | Convert resident savings accounts to NRE/NRO accounts immediately upon attaining NRI status under FEMA. |
| Consult a Tax Expert | Seek guidance from a CA or tax advisor specializing in NRI taxation to comply with both US and Indian laws, and to claim DTAA benefits. |
| Maintain Documentation | Keep supporting documents like passport entry/exit stamps, bank statements, and Tax Residency Certificates (TRC) for filings. |
| Track Indian-Sourced Income | Record all Indian income carefully to ensure accurate reporting and avoid penalties. |
| File Returns and TDS on Time | Ensure timely filing of ITR and TDS obligations in India and US reporting (FBAR, IRS forms). |
| Evaluate Investments & Property | Review Indian investments and property ownership to check tax implications and compliance with FEMA restrictions. |
Conclusion
For Indian NRIs in the USA, careful planning and proper understanding of residential status are essential for income taxation. Correct classification ensures compliance with income tax, capital gains tax, and reporting obligations, while helping claim any eligible refund. A clear understanding of taxation of capital gains and tax income rules can save NRIs from unnecessary penalties and optimize their overall tax position.